UKG Wallet

- 1.86K Reviews
- 4.5
- Downloads
- 100,000+
Our take on UKG Wallet from Appgk
Getting paid is usually a simple idea, but the timing behind it can be frustrating. UKG Wallet is a business app built around giving employees access to wages they have already earned, rather than making them wait for the usual payday. I found its appeal easy to understand: it is not trying to replace a full bank, budgeting suite, or payroll system. It focuses on the space between working and receiving money, which can matter when an unexpected bill arrives before the next scheduled payment.
The app is developed by UKG, Inc. and is available free of charge for Everyone. It has reached over one hundred thousand installs, with an average rating of 4.5 from around twelve thousand ratings and roughly two thousand reviews. Those figures suggest that the basic idea is useful to many people, although they do not remove the most important condition: your employer must support the service and your wages must be available through the system.
How UKG Wallet feels in everyday use
My first impression is that UKG Wallet makes more sense as an employee benefit than as a general-purpose finance app. The central question is not “How do I manage every part of my money?” but “Can I access part of what I have already earned before payday?” That narrower purpose is also its strength. The experience is easier to understand when you treat it as a bridge between earned income and your normal bank account.
A realistic example would be a worker who has completed several shifts, then discovers that a utility payment is due before the regular payroll date. Instead of applying for a small loan or using a credit card, that person can check whether earned wages are available and decide whether moving some of that money is worthwhile. The useful part is the timing: the app can help turn completed work into a more immediate source of funds.
Best Parts of UKG Wallet
Things to Keep in Mind About UKG Wallet
That does not mean I would use it automatically every time money becomes available. Early access can solve a short-term problem, but it can also make the next regular payday feel smaller. I think the best habit is to open the app with a specific purpose, check the amount available, and take only what is needed. Used that way, it can be a practical safety valve rather than a replacement for planning around the normal pay cycle.
The app’s business category is important because it tells you what kind of experience to expect. This is connected to employment and payroll, not a standalone wallet that anyone can open and fund independently. If you are self-employed, paid through an unrelated payroll provider, or looking for a conventional digital bank, UKG Wallet is probably not the right starting point.
News and Features Related to UKG Wallet

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
The employer connection changes the whole experience
Unlike a typical banking app, the usefulness of UKG Wallet depends on the workplace behind it. Your employer’s payroll setup, eligibility rules, and processing schedule influence what you can actually do. That means two employees in different organizations may not see exactly the same practical value, even when they are using the same application.
This is the first detail I would check before spending time learning the app: ask your employer whether UKG Wallet is supported for your role and how earned wages are handled. A polished interface cannot overcome an unsupported payroll arrangement. It is also worth confirming whether the amount shown reflects completed work, processed time, or another internal calculation, because the balance should be treated as an estimate of accessible earnings until the app makes it available for use.
Don't want to read the full review?
That employer dependency is a trade-off. It makes the service more relevant than a generic money app because it can be tied to actual employment information, but it also gives the user less control over setup. A normal bank account belongs to you regardless of where you work. UKG Wallet is more specialized, and that specialization is exactly why it may be valuable to one employee and irrelevant to another.
What the current version tells me
The current version is 1.0.25, while the app was released on December 21, 2021. I read that combination as a sign of an established product that has continued through successive updates rather than remaining at its original launch state. It is not sensible to treat a version number alone as proof of a major redesign, but it does show that the app has had room to evolve after its initial release.
Screenshots
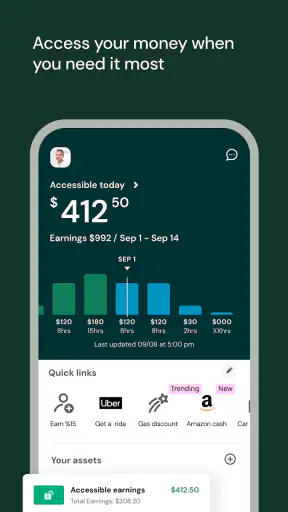
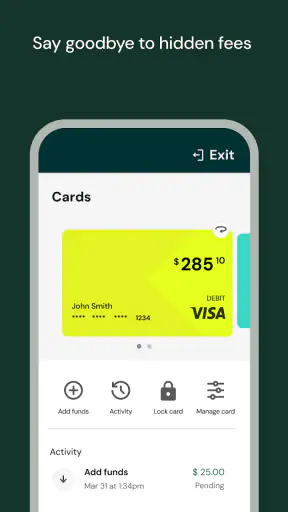
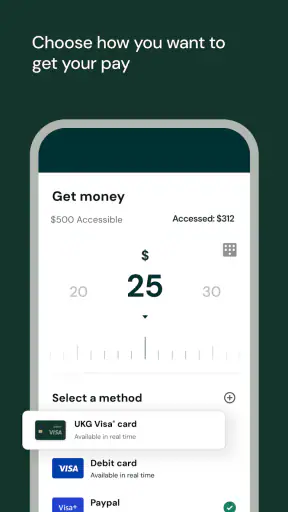
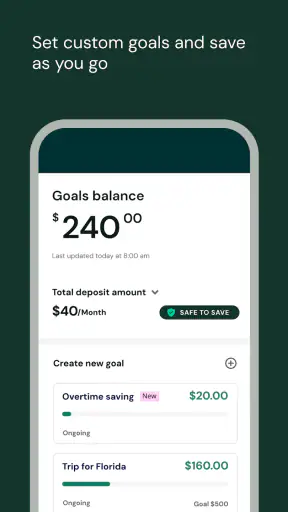
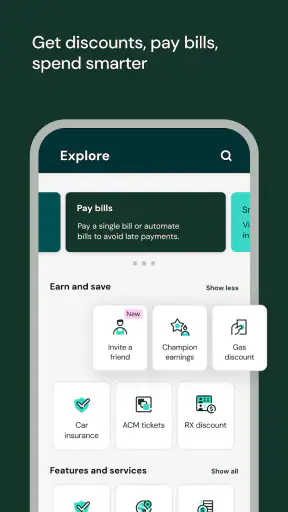
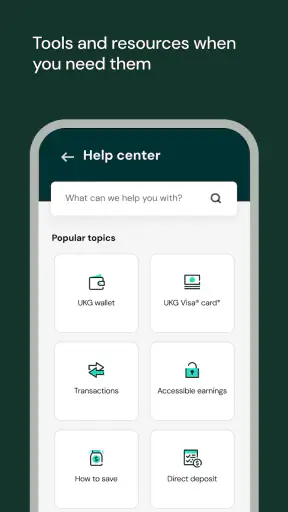
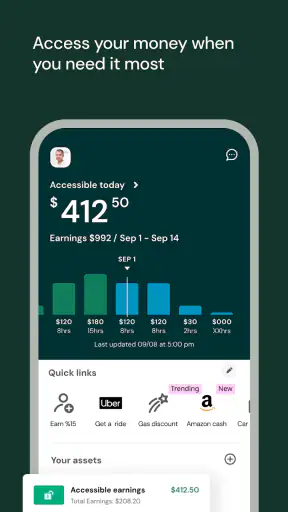
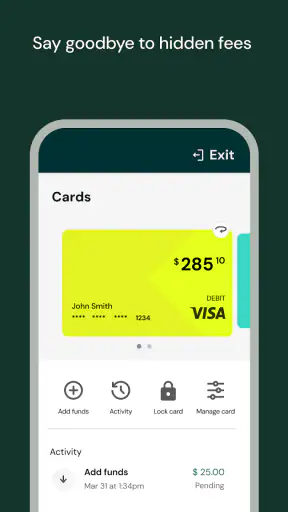
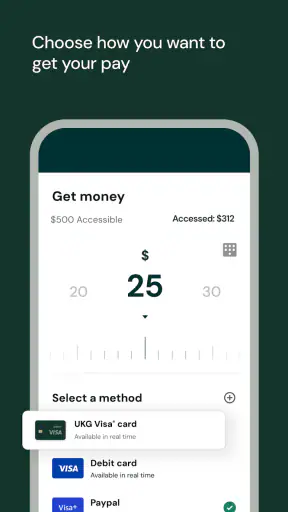
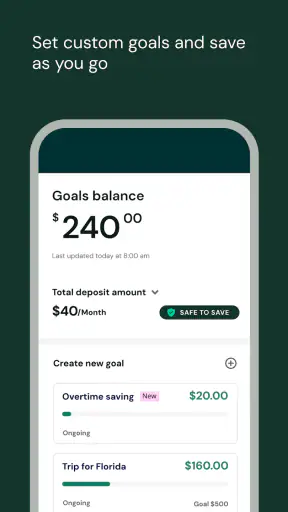
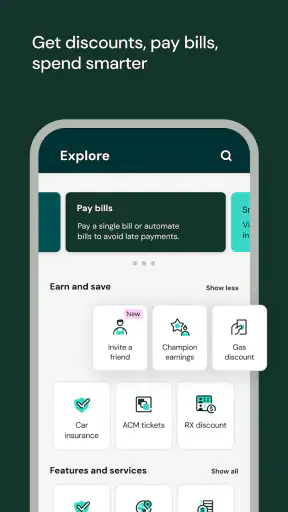
For an existing user, the practical lesson is to keep the installed app current instead of relying on an older build. Financial and payroll tools need to remain aligned with the systems they connect to, and an update can matter even when the visible interface changes only slightly. I would also avoid judging the service entirely from an early experience, because later releases may improve the flow, resolve device-specific issues, or adjust how information is presented.
At the same time, I would keep expectations grounded. The version history does not turn UKG Wallet into a full financial planner. Its identity remains focused on access to earned wages. If you install it expecting detailed investment tools, broad account aggregation, or the extensive controls of a traditional bank, you may conclude that it is limited when the real issue is that it was designed for a different job.
Small workflow choices that make it more useful
The most useful way to approach the app is to separate checking from transferring. First, I would use it to understand whether earned wages are currently available. Only after confirming the amount would I decide whether to move money. This two-step habit reduces impulsive withdrawals and makes the app more like a planning checkpoint than a button for instant spending.
I would also check the balance after a meaningful work period rather than repeatedly refreshing it throughout the day. Payroll-related information may not appear at the same moment a shift ends, so constant checking can create unnecessary confusion. If the amount does not change immediately, that does not automatically mean the app is broken; the underlying employment and payroll process may need time to update.
Another practical tip is to compare the available amount with the next week’s obligations before taking anything. Someone who uses early wages for a grocery trip today may still need to cover transport, rent, or a scheduled bill later. The app can improve flexibility, but it cannot make the same earnings cover two separate periods without consequences. That is the central trade-off I would explain to a friend before recommending it.
For people who share household expenses, the app may also be useful as a timing tool. If one paycheck normally arrives after a joint bill is due, accessing a limited amount of earned pay could help avoid a late payment. I would still keep records outside the app, perhaps in a simple note or budget, because the wallet’s purpose is access rather than complete household accounting.
Where it compares well with familiar alternatives
The usual alternatives are a credit card, an overdraft facility, a small personal loan, or simply waiting for payday. UKG Wallet has an obvious advantage over borrowing: it is built around wages that have already been earned. That can make the idea easier to understand than taking on a separate debt for a short-lived cash shortage.
It can also be more targeted than a standard banking app. A bank may show your current balance and recent transactions, but it generally does not provide the same employment-focused view of wages waiting for the regular payroll date. UKG Wallet’s value comes from connecting the work you have completed with the money you may be able to access.
However, a bank remains better for broader money management. If your main goal is saving, paying bills, moving money between accounts, or reviewing long-term spending, a conventional banking app will usually be the more complete tool. A credit card may also be more suitable for a purchase that must be paid later, provided you understand the repayment cost. UKG Wallet is strongest for a narrow timing problem, not every financial decision.
I would be especially cautious about comparing it with a loan as though the two products were interchangeable. Accessing earned wages may avoid borrowing in a traditional sense, but it still changes when your income reaches you. The financial pressure has not disappeared; it has moved forward. That distinction is easy to overlook when the interface presents available money in a convenient way.
The friction existing users should expect
The biggest limitation is the dependency on employment data. If hours, shifts, or payroll information are delayed or interpreted differently from what you expect, the amount shown may not match your own calculation. That can be frustrating for someone who wants an immediate answer after working. In that situation, the sensible next step is to compare the app with your employer’s timekeeping or payroll records rather than assuming the wallet alone has the final word.
Another point is that access to wages does not necessarily mean every amount is available at every moment. The app’s usefulness is shaped by employer participation and the way earnings are processed. I would therefore avoid promising yourself that a particular expense will be covered until the money is actually accessible and you understand how it will affect the next regular payment.
The focused design may also feel sparse to people who want a complete financial dashboard. UKG Wallet is not where I would expect to manage investments, build a detailed spending plan, or organize every account in one place. That is not a flaw in the narrow wage-access purpose, but it is a genuine gap if you want one app to handle your entire financial life.
There is also a behavioral risk. Convenient access can encourage a cycle in which each payday is partly consumed in advance. I would not recommend the app to someone who already struggles to make a fixed paycheck last and is likely to treat accessible wages as extra income. In that case, a budgeting tool, direct conversation with payroll, or a more structured savings plan may be more helpful than faster access.
Who should install it and who should skip it
I see UKG Wallet as a strong candidate for employees whose workplace supports it and who occasionally face a gap between earning money and needing to pay for something. It may be particularly helpful for workers with variable schedules, because the ability to see earned wages can make cash-flow decisions less dependent on guesswork. The service is also approachable for someone who does not want to apply for credit for a relatively small, short-term need.
I would recommend skipping it if your employer does not use the relevant UKG payroll arrangement, if you are looking for a normal checking account, or if you want advanced budgeting and financial planning in the same place. It is also not a good solution for a permanent income shortfall. Faster access can help with timing, but it cannot fix expenses that consistently exceed earnings.
The Everyone age rating makes the app broadly accessible from a content perspective, but that should not be confused with universal eligibility as an employee service. The important question is not whether the app is suitable for a particular age group in the store; it is whether your employment situation connects you to the service and whether using early access fits your finances.
What to watch as the product continues to evolve
Because the app has moved beyond its original release and is now at version 1.0.25, I would watch future changes in three areas. First, clarity matters: users should be able to understand why a certain amount is available, when it was earned, and how accessing it affects the ordinary payroll cycle. Better explanations would be more valuable to me than decorative interface changes.
Second, I would pay attention to how the experience handles exceptions. Delayed time records, corrected shifts, payroll adjustments, and changes in employment status are the moments when a wage-access app proves whether it is genuinely dependable. A smooth normal-day workflow is useful, but clear guidance during an irregular payroll situation is even more important.
Third, I would look for improvements that help users make deliberate choices rather than simply encouraging faster withdrawals. Helpful reminders, transparent transaction status, and a clear view of upcoming regular pay could make the app safer to use. I am not treating those possibilities as existing features; they are the areas I would want the developer to prioritize as the product develops.
For current users, the best approach is to keep the app updated, learn how your employer’s payroll timing affects the displayed balance, and use early access for defined needs. If the app ever shows information that conflicts with your work records, resolve the discrepancy through the appropriate workplace channel instead of repeatedly relying on the displayed figure.
My final take on the wallet
After looking at UKG Wallet as both a practical tool and a financial habit, I think its value is real but specific. It gives supported employees a way to think about income in relation to work already completed, which can be genuinely useful when a bill arrives before payday. The free price and focused purpose make it easy to consider, and the strong average rating indicates that many users find the experience worthwhile.
The best reason to use UKG Wallet is controlled flexibility, not extra money. That distinction sums up my opinion. I would recommend it to a friend who needs occasional breathing room and is willing to check the consequences before accessing wages. I would not recommend it as a substitute for a bank, a budget, or a plan for recurring financial difficulty.
UKG, Inc. has built an app that addresses a recognizable workplace problem without pretending to be an all-in-one financial solution. Its future success will depend on how clearly it explains wage availability, how well it handles payroll exceptions, and whether updates continue to improve confidence for existing users. For the right employee, it can be a useful bridge. For everyone else, a normal banking or budgeting app will likely be the better fit.
UKG Wallet FAQ
What is UKG Wallet and what does it do?
UKG Wallet is a financial wellness feature connected with eligible UKG workforce-management and payroll systems. It may allow employees to view available earned wages, access funds before the regular payday, review payment activity, and manage related financial tools from a mobile device. The exact features depend on your employer’s UKG setup, payroll configuration, location, and eligibility, so the app may look different for every user.
Who can use UKG Wallet, and how do I sign up?
UKG Wallet is generally intended for employees whose organizations have enabled the service through an applicable UKG solution. You normally need valid employee credentials, personal identification details, and sometimes a verification step before accessing wallet features. Downloading the app alone does not guarantee access. If your employer has not activated UKG Wallet, or your employment information is not eligible, you may be unable to register or use earned-wage features.
Can UKG Wallet give me access to my wages before payday?
In supported workplaces, UKG Wallet may provide access to a portion of wages already earned but not yet included in your normal paycheck. Availability, limits, timing, and any applicable charges can vary according to your employer’s policies, payroll processing, state or country regulations, and the payment method you select. It is important to review the transaction details and understand that early access can affect the amount received on your regular payday.
Is UKG Wallet safe to use for payroll and personal information?
UKG Wallet handles sensitive employment, identity, and payment information, so users should treat it like any other financial application. Use the official app store listing, create a strong unique password when required, enable available security protections, and never share verification codes. Before confirming a transfer, check the recipient and amount carefully. For privacy details, permissions, security questions, or suspicious activity, consult the official UKG support resources or your employer’s administrator.
Are there fees or limitations when using UKG Wallet?
Some UKG Wallet services may be free, while particular transfer options, expedited delivery methods, or third-party financial services could involve fees. Limits may also apply to the amount or frequency of wage access, account transfers, card usage, or withdrawals. Because pricing and restrictions can differ by employer, location, and product configuration, review the fee disclosure shown inside the app before confirming a transaction and contact your payroll or HR department if anything is unclear.